
Published September 22, 2026
Unincorporated Aurora Real Estate: Avoid the $15,000 Private Utility Trap Triggering Loan Failures
How Hidden Septic and Well Issues Stop Mortgages in Unincorporated Aurora—and How Homebuyers Can Protect Their Earnest Money
You find the perfect Chicagoland property: a spacious lot, lower property taxes, mature trees, and classic suburban charm. The address says Aurora, Illinois, the price is right, and your offer is accepted.
Then, three weeks into escrow—just days before closing—your mortgage underwriter issues an abrupt denial or a conditional "clear to close" that requires an unexpected $15,000 private utility repair or municipal hookup.
This scenario plays out repeatedly across Unincorporated Aurora real estate. Buyers naturally assume that an "Aurora" address guarantees municipal city water and sewer services. However, parcels located in unincorporated Kane or DuPage County fall outside city limits and operate under an entirely different set of rules, systems, and mortgage underwriting criteria.
At The Saladino Sells Team, we believe that transparency is the key to a stress-free real estate experience. Below is a breakdown of why unincorporated parcels trigger last-minute loan failures, where the hidden costs lie, and how to protect your earnest money deposit.
What Is "Unincorporated Aurora" Real Estate?
When a property has an Aurora mailing address but sits in Unincorporated Kane County or Unincorporated DuPage County, it is governed by county jurisdiction rather than the City of Aurora.
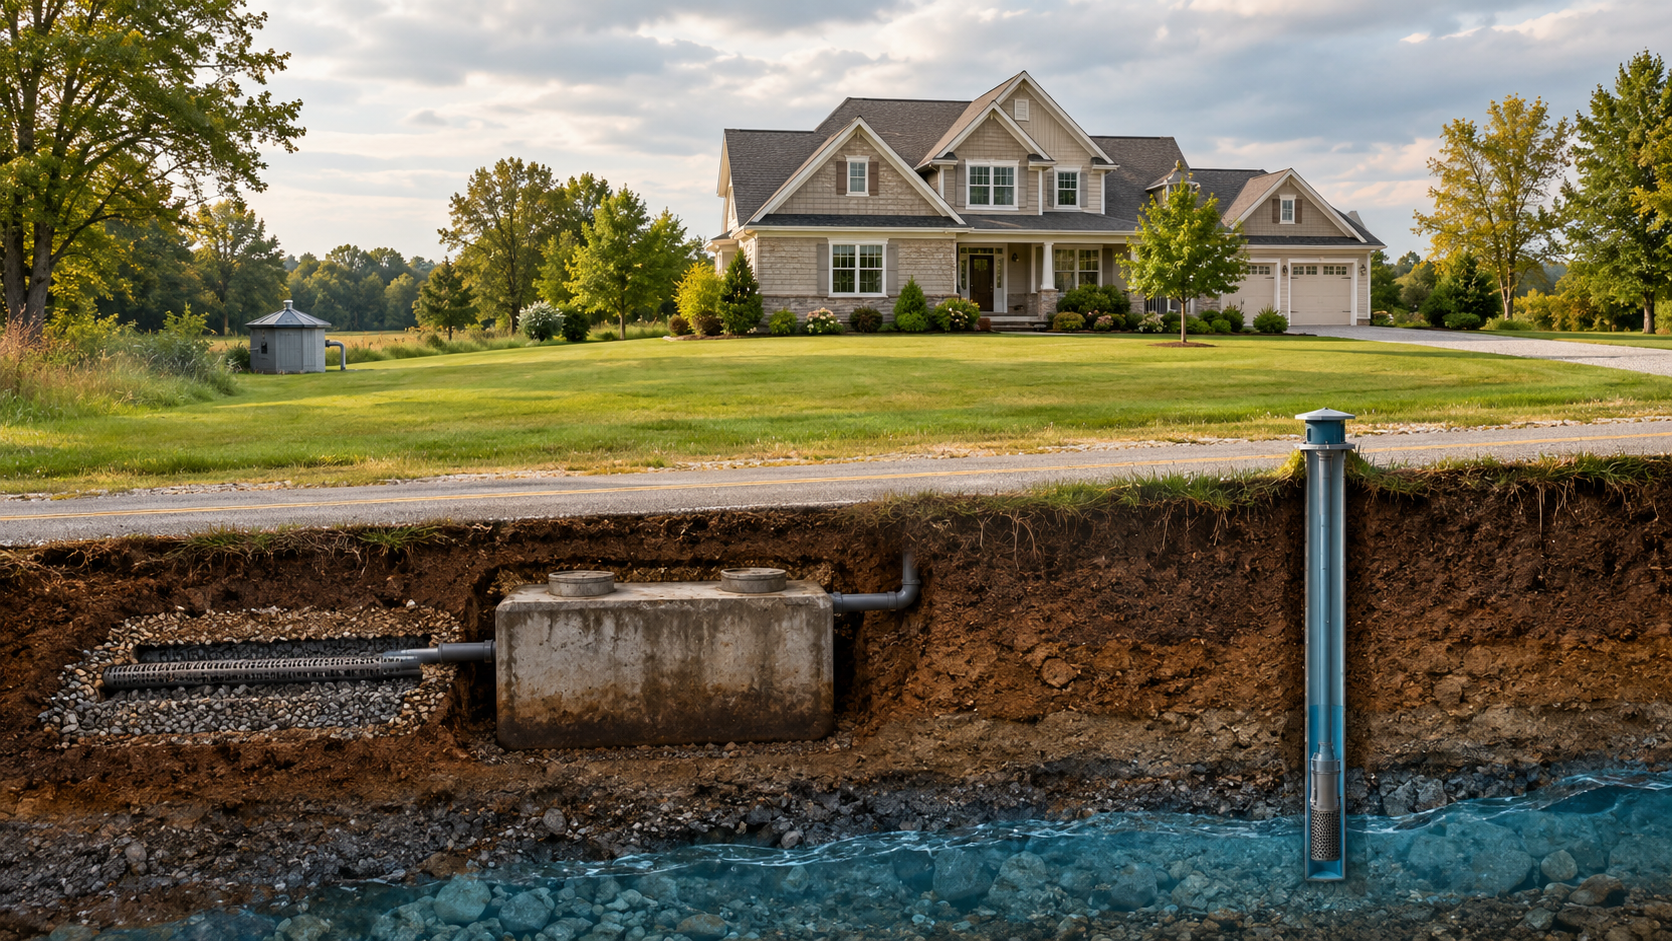
While this often comes with benefits like larger lot sizes and reduced property tax rates, it also means the property is typically disconnected from municipal infrastructure. Instead of city water and public sewers, these homes rely on:
-
Private Water Wells
-
On-Site Septic Tank Systems
-
Private or Shared Utility Maintenance Agreements
Why Private Utilities Trigger Loan Failures
Mortgage lenders (including Conventional, FHA, VA, and USDA loan underwriters) treat private utilities with extreme scrutiny. They view an unsafe well or a failing septic tank not just as a maintenance issue, but as a direct threat to the property's overall collateral value and habitability.
Here are the primary ways an unincorporated parcel can derail your financing during escrow:
1. Failed Well Water Quality & Flow Tests
Lenders require comprehensive water testing for private wells. If tests reveal elevated levels of nitrates, coliform bacteria, heavy metals, or volatile organic compounds (VOCs), the underwriter will immediately suspend loan approval. Rectifying these issues requires filtration systems, well-head repairs, or drilling a new well—costing anywhere from $3,000 to $12,000+.
2. Strict Well-to-Septic Separation Rules
FHA and VA loan guidelines mandate rigid minimum separation distances between private utilities:
-
FHA Requirement: Minimum 50-foot distance between a private well and a septic tank.
-
FHA Requirement: Minimum 100-foot distance between a private well and the septic tank drain field (can drop to 75 feet if local health authority permits).
-
Property Line Distance: Minimum 10-foot distance from property boundaries.
In older Unincorporated Aurora neighborhoods, homes built decades ago frequently violate modern separation guidelines. If a lot is too small to adjust the distance, obtaining an underwriting exception requires complex variance approvals—or an outright loan denial.
3. Septic System Operational Failures
Unlike a standard home inspection, a full septic dye or camera inspection tests the physical absorption field. If the system shows effluent pooling, tank degradation, or field saturation, county health codes mandate a complete repair or replacement. A full septic replacement in northern Illinois routinely ranges between $10,000 and $25,000.
4. Mandatory Municipal Annexation Mandates
In certain pockets of unincorporated Aurora, local health codes or municipal ordinances dictate that if a private septic system fails within a specific proximity to an existing municipal sewer line (e.g., within 200–300 feet), you cannot repair the septic system. Instead, you are legally required to annex into the city and connect directly to public utilities.
This "forced hookup" includes:
-
City connection and tap fees
-
Permitting and engineering costs
-
Trenching and pipe installation across your property
-
Decommissioning and backfilling the old septic tank
Total unexpected cost: Easily $15,000 to $30,000+. If neither the buyer nor the seller has liquid cash reserved to cover this expense before closing, the deal collapses.
The $15,000 Private Utility Action Plan
If you are evaluating homes for sale in Unincorporated Aurora, build these four protective steps directly into your offer process:
STEP 1: Verify Municipal Status Early
Never rely solely on the listing address. Have your real estate agent verify the parcel number (PIN) with Kane or DuPage County tax records to confirm whether it is incorporated or unincorporated.
STEP 2: Add Specific Utility Contingencies
Ensure your Attorney Review and Inspection Contingency clauses explicitly name well water potability/flow testing and septic system camera/dye testing. Standard home inspectors do not perform exhaustive well and septic certifications.
STEP 3: Obtain a Modern Property Survey
Request an updated boundary survey showing the exact location of the well head, septic tank, and absorption field relative to lot lines.
STEP 4: Consult Your Lender on FHA/VA Rules
If using government-backed financing, notify your mortgage originator immediately that the home uses private utilities so distance guidelines are verified early in the process.
If the utilities pass inspection: Proceed confidently to mortgage underwriting.
If the utilities fail inspection: Require seller repairs/credits prior to closing, check for mandatory city hookup requirements, or safely exit the contract with your earnest money intact using your contingency clauses.
Protect Your Investment with The Saladino Sells Team
Navigating Chicagoland real estate requires localized market expertise that goes deeper than superficial listing photos. From understanding complex zoning boundaries to identifying hidden infrastructure pitfalls, working with an experienced team prevents costly surprises before you reach the closing table.
Whether you are looking to buy an acreage property in Unincorporated Aurora or selling a home in the greater Chicago suburban market, The Saladino Sells Team provides the strategic guidance and rigorous contract protection you deserve.
Ready to start your search with confidence? Contact The Saladino Sells Team today for a personalized strategy consultation on your next home purchase.
Michael Saladino
Managing Broker | Saladino Sells Team | Keller Williams ONEChicago | PLACE
or another way